

Market infrastructure, traceability and regulatory compliance are no longer competitive advantages. They have become concrete requirements for anyone operating with stablecoins in Brazil at significant volume.
And the figures released by Brazil’s Federal Revenue Service in early 2026 make this reality impossible to ignore.
What do the numbers on stablecoins in Brazil really say?
Between August 2019 and December 2025, stablecoins accounted for 71% of the total value moved in declared crypto asset transactions in the country, equivalent to R$ 1.13 trillion out of a total of close to R$ 1.58 trillion.
In the most recent periods, this share exceeded 80% of monthly volume, with a peak of R$ 39.7 billion recorded in November 2025.
This is not a niche figure. It is a structural figure for the Brazilian financial system.
The number of declared transactions reinforces the scale: 185.7 million transactions in the period analyzed, with a monthly record of 18.2 million in November 2024. The concentration in USDT is equally striking:
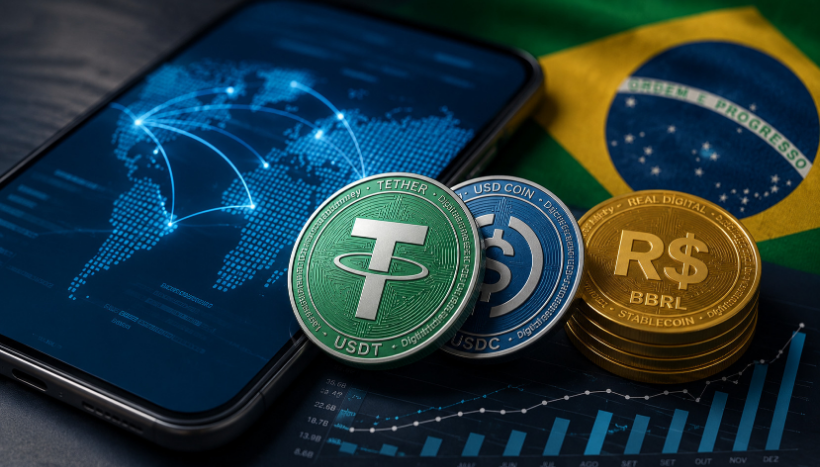
- Tether (USDT): 88.7% of the stablecoin market
- USDC (Circle): 7.1%
- BRZ (Brazilian real): 3.4%
The question this scenario raises is not “have stablecoins grown?”. The relevant question is: what does this market structure reveal about how Brazil’s digital financial system really works?
Why has the Brazilian market shifted so heavily toward stablecoins?
The dominance of stablecoins is not an accident. It is a rational response to a set of structural frictions in Brazil’s traditional financial market.
What is the real role of stablecoins for those operating in the Brazilian market?
For most institutional operators and digital asset platforms, stablecoins serve three distinct, and often simultaneous, functions:
- Operational liquidity: they act as a medium of exchange between digital assets, removing the need to convert to fiat currency for every transaction
- Indirect currency hedging: they allow exposure to the US dollar without going through the traditional banking system, at lower cost and higher speed
- International transfer instrument: they enable cross-border remittances and settlements outside the conventional correspondent banking structure
These uses explain why USDT accounts for nearly 90% of the market. It is not an aesthetic preference, it is about function.
Tether has global liquidity, is available on the main exchanges and offers the lowest spread on entry and exit transactions between markets.
Are stablecoins a dollar substitute, a currency hedge or an operational instrument?
The honest answer is: it depends on who is operating and for what purpose. For individual investors, stablecoins often work as accessible dollarization, a way to hold reserves in dollars without opening an account abroad.
For institutional operators and platforms, the role is primarily operational: stablecoins are the “rail” on which transactions move.
This distinction matters from a regulatory standpoint. The Central Bank and the Federal Revenue Service are not looking at stablecoins as a curiosity. They are looking at a volume that already has systemic relevance and that, to a significant extent, flows through providers based abroad, outside the domestic supervisory perimeter.
What does the dominance of stablecoins reveal about the structure of Brazil’s digital asset market?
When stablecoins account for more than 80% of the monthly volume of a market that moves tens of billions of reais, they stop being an instrument within the market and become that market’s operational backbone.
This has direct implications for asset tokenization and for structuring operations in the digital financial market:
- Stablecoin liquidity is a condition for tokenized assets to be traded efficiently
- The traceability of stablecoin transactions is what allows the regulatory environment to work; without it, the reporting required by DeCripto does not add up
- The concentration in foreign providers represents a regulatory bottleneck that the Central Bank has already identified and is addressing
Extending DeCripto reporting obligations to foreign providers operating in Brazil, in line with the OECD Crypto-Asset Reporting Framework, is a direct response to this bottleneck.
The regulator realized that a significant portion of the volume was outside the supervisory perimeter and acted to correct it.
For those thinking about the future of the digital capital market in Brazil, this regulatory move is a clear signal: the supervisory environment will become broader, not narrower.
What do recent regulatory moves say about the Central Bank’s view?
Three moves in early 2026 show precisely how the regulator is responding to the volume and systemic relevance that stablecoins have reached.
- Suspension of foreign exchange for crypto funds (June 2026)
The Central Bank notified market institutions, ordering the immediate halt of foreign exchange transactions related to the import of virtual assets carried out by investment funds.
The Central Bank’s view is that when a fund starts intermediating the purchase and sale of virtual assets on behalf of third parties, its activity comes close to providing virtual asset services, which falls under the PSAV regime [LINK PARA O ARTIGO O que muda para PSAVs com a entrada no arcabouço prudencial do Sistema Financeiro?].
The market disputes this, arguing that funds act on their own account under CVM supervision. The practical result, for now, is more conservative structures and an impact on pricing.
- Proposed 24-hour hold on transfers abroad
The Central Bank proposed a rule requiring a hold of up to 24 hours on transfers of funds abroad via stablecoins above US$ 10,000.
The measure is described as precautionary, aimed at preventing fraud, and allows early release based on a risk analysis consistent with the client’s profile.
The proposal would be implemented through an update to BCB Resolution 142/2021.
- Extension of DeCripto to foreign providers
The reporting obligation now covers providers based abroad that operate in Brazil, aligning the country with the OECD’s CARF standard.
This means that volume that previously flowed outside the domestic regulator’s radar is now subject to reporting obligations, with direct consequences for platforms operating in this structure.
These three moves are not isolated threats. They are coordinated signals that the supervisory framework is being calibrated to the volume the market has reached.
What does this scenario mean for those operating with stablecoins in the regulated market?
The practical question for asset managers, platforms and structurers is straightforward: how does your current operation hold up under this regulatory framework?
Those operating with stablecoins at significant volume face three concrete challenges:
- Structured reporting: DeCripto requires accurate reporting of every transaction, including volume, counterparty and nature. Without native traceability in the infrastructure, this becomes a growing operational cost
- Real-time risk analysis: the proposed 24-hour hold requires the provider to demonstrate risk analysis capabilities consistent with the client’s profile, which presupposes KYC/AML integrated into the operation
- Legal classification of structures: the controversy over crypto funds shows that the boundaries of what is allowed are being actively redefined. Operating in a gray area has an expiration date
This is exactly the context in which BLOCKBR’s asset tokenization infrastructure for the regulated financial market becomes operationally relevant, not as a market differentiator, but as a condition for operating with legal certainty within this environment.
How do compliance, traceability and reporting become structural requirements rather than optional ones?
The logic is simple: when stablecoin volume in Brazil reaches R$ 1.13 trillion in six years and the regulator starts requiring every transaction to be reported with counterparty identification, compliance needs to be built into the architecture of the operation, not handled through manual processes after the fact.
Platforms that structure stablecoin operations using BLOCKBR’s infrastructure operate with native traceability, integrated reporting and KYC/AML as a structural layer, not an add-on. This means that the tokenization of assets involving stablecoin settlement is born within the required compliance perimeter.
BLOCKBR Station acts as a regulatory integration hub in this context, connecting regulated agents (DTVM, custody, registration) to the operation so that every transaction has end-to-end traceability. For operations that involve reporting to the Federal Revenue Service via DeCripto, this integration stops being a convenience and becomes an operational requirement.
For platforms that want to operate with stablecoins within the regulated environment without building each compliance layer separately, BLOCKBR Whitelabel offers an integrated legal and technological foundation, which reduces the time and risk of structuring an operation that is born at the regulatory level required by the Central Bank and the Federal Revenue Service.
This is especially relevant at a time when the regulation of receivables tokenization and other digital assets is being actively calibrated.
Stablecoin volume in Brazil is no longer a crypto market figure. It is a financial system figure.
The regulator and the Federal Revenue Service have already noticed. The operational question for platforms, asset managers and structurers is not whether this environment will become more supervised. It is whether the current operation is ready to function within it.
Explore BLOCKBR’s infrastructure and see how to structure stablecoin operations within the regulated market.
Frequently asked questions about stablecoins in Brazil
What are stablecoins and how do they work?
Stablecoins are digital assets whose value is pegged to a reference currency, usually the US dollar. They work as a digital representation of a currency: each unit of USDT, for example, corresponds to one dollar held in reserve by the issuer.
What sets them apart from other crypto assets is price stability, which makes them useful as a medium of exchange, a settlement instrument and a store of value within the digital asset market.
Why do stablecoins dominate the crypto asset market in Brazil?
Their dominance reflects practical functions: stablecoins allow exposure to the dollar with less friction than the traditional banking system, act as a liquidity rail between digital assets and enable international transfers outside the conventional correspondent banking structure.
In Brazil, where the foreign exchange spread and the cost of accessing dollars are significant, this combination of functions explains the concentration of volume.
USDT, USDC and BRZ: what is the difference between the main stablecoins in the Brazilian market?
USDT (Tether) dominates with 88.7% of the Brazilian stablecoin market, has global liquidity and is available on the main exchanges.
USDC (Circle), with 7.1%, is issued by a company regulated in the US and offers greater transparency about its reserves, making it the preferred choice in institutional contexts.
BRZ, with 3.4%, is pegged to the Brazilian real and serves specific use cases that do not involve exposure to the dollar.
Are stablecoins regulated in Brazil?
Yes. Stablecoins pegged to foreign currencies fall within the concept of a virtual asset under Central Bank regulation, which began supervising virtual asset service providers (PSAVs) in 2023.
The Federal Revenue Service requires transactions to be reported via DeCripto. And the Central Bank is actively adjusting its rules, such as the proposed 24-hour hold, to calibrate the supervisory framework to the volume the market has reached.
What is DeCripto and how does it affect those operating with stablecoins?
DeCripto is the Federal Revenue Service’s reporting system for crypto asset transactions. It requires providers, now including those based abroad that operate in Brazil, to report every transaction with counterparty identification, volume and nature.
For those operating with stablecoins at significant volume, this means that traceability and structured reporting are not options, they are obligations with penalties for non-compliance.
What does the Central Bank’s proposed 24-hour hold mean for stablecoin transactions?
The proposal requires virtual asset service providers to hold transfers abroad via stablecoins above US$ 10,000 for up to 24 hours, allowing a risk analysis consistent with the client’s profile before release.
For platforms, this means KYC/AML needs to be integrated into the operational flow, not run as a parallel process. Those already operating on infrastructure with native risk analysis can absorb this requirement without restructuring their operations. Those without it need to hurry.